A Loan Payable occurs when your company borrows money from a bank or another company. The money comes into your bank account, but it is not income — it is a liability, because you are obligated to repay it. The loan principal is tracked in 21000 Loans Payable. Interest incurred on the loan is recognized as 90100 Interest Expense.
1. Receiving a loan from a bank or another company #
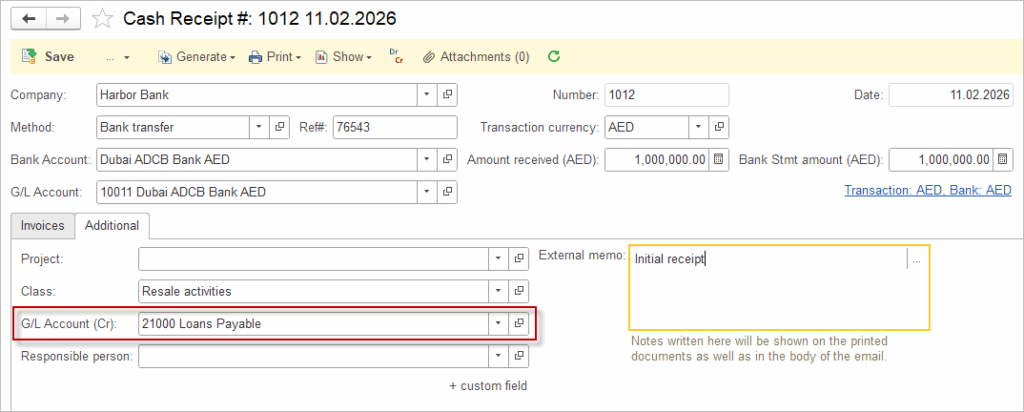
When the loan proceeds are deposited into your bank account, you record the liability.
| Document | Debit | Credit |
|---|---|---|
| Deposit / Cash Receipt | 10000 Bank Accounts (or 10011 Bank Account Currency) | |
| 21000 Loans Payable |
Cash has increased, and a liability has been created. Total assets and total liabilities both increase.
2. Accruing interest on a loan payable #
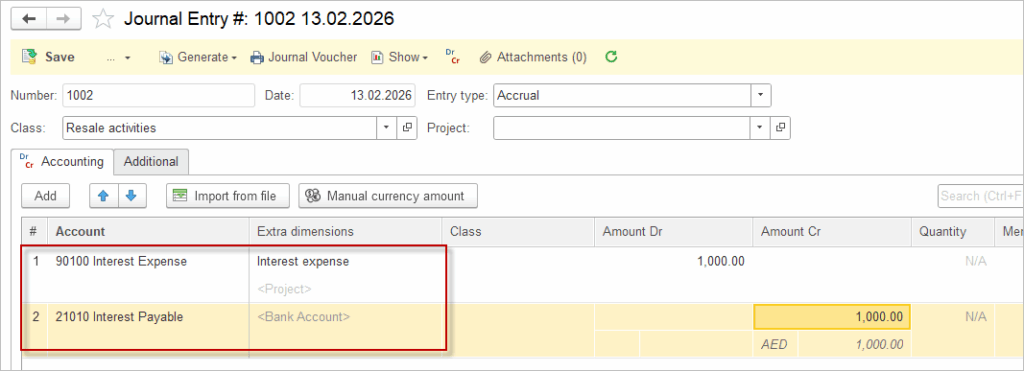
At the end of each period, you accrue interest that has been incurred but not yet paid.
| Document | Debit | Credit |
|---|---|---|
| Journal Entry | 90100 Interest Expense | |
| 21100 Interest Payable |
This entry matches the interest expense to the period in which it was incurred, following the accrual basis of accounting.
Use Recurring Templates to schedule repeatable accruals.
3. Repaying the loan (principal + interest) #
When you make a payment to the lender, the payment typically covers both principal and interest. You must split the payment.
| Document | Debit | Credit |
|---|---|---|
| Payment | 21000 Loans Payable (principal portion) | |
| 90100 Interest Expense or 21100 Interest Payable (interest portion) | ||
| 10000 Bank Accounts (or 10011 Bank Account Currency) |
If interest was already accrued in step 2, you debit 21100 Interest Payable. If it was not accrued, you debit 90100 Interest Expense directly.
4. Loan received from a related company (intercompany loan) #
If the lender is a related company rather than a bank, the accounting treatment is the same — the only difference is the counterparty.
| Document | Debit | Credit |
|---|---|---|
| Deposit / Cash Receipt | 10000 Bank Accounts | |
| 21000 Loans Payable |
For reporting purposes, you may want to create a sub-account such as 21001 Loans Payable — Related Parties to distinguish intercompany loans from bank loans.