A Loan Issued occurs when your company lends money to another company or to an employee. The money leaves your bank account, but it is not an expense — it is an asset, because you expect to receive it back. The loan principal is tracked in 16000 Loans Issued (for loans to companies) or 16300 Employee Loans (for loans to employees). Interest earned on the loan is recognized as 80100 Interest Income.
If you give loan to your employee and after get back part of his payroll as a deduction then use Employee Loans Issued scheme.
Note: The interest income account (
80100 Interest Income) must be included in the taxable base for Profit/Corporate Tax – it is not taxed line-by-line at the time of accrual, but as part of the overall taxable profit for the period.
1. Issuing a loan to another company #
When you transfer funds to the borrower, you record the loan as an asset.
| Document | Debit | Credit |
|---|---|---|
| Payment | 16000 Loans Issued | |
| 10000 Bank Accounts (or 10011 Bank Account Currency) |
The loan principal is now recorded as an asset. Cash has decreased, but total assets remain unchanged – one asset (cash) is converted into another asset (loan receivable).
2. Issuing a loan to an employee #
Employee loans are tracked separately for reporting and reconciliation purposes.
| Document | Debit | Credit |
|---|---|---|
| Payment | 16300 Employee Loans | |
| 10000 Bank Accounts (or 10011 Bank Account Currency) |
3. Accruing interest on a loan issued #
If the loan is interest-bearing, you recognize interest income at the end of each period, even if the borrower has not yet paid it.
| Document | Debit | Credit |
|---|---|---|
| Journal Entry | 16100 Interest Receivable | |
| 80100 Interest Income |
For long-term loans, you may use 17100 Long-term Interest Receivable instead of 16100 Interest Receivable.
Use Recurring Templates to schedule repeatable accruals.
4. Receiving a repayment from the borrower #
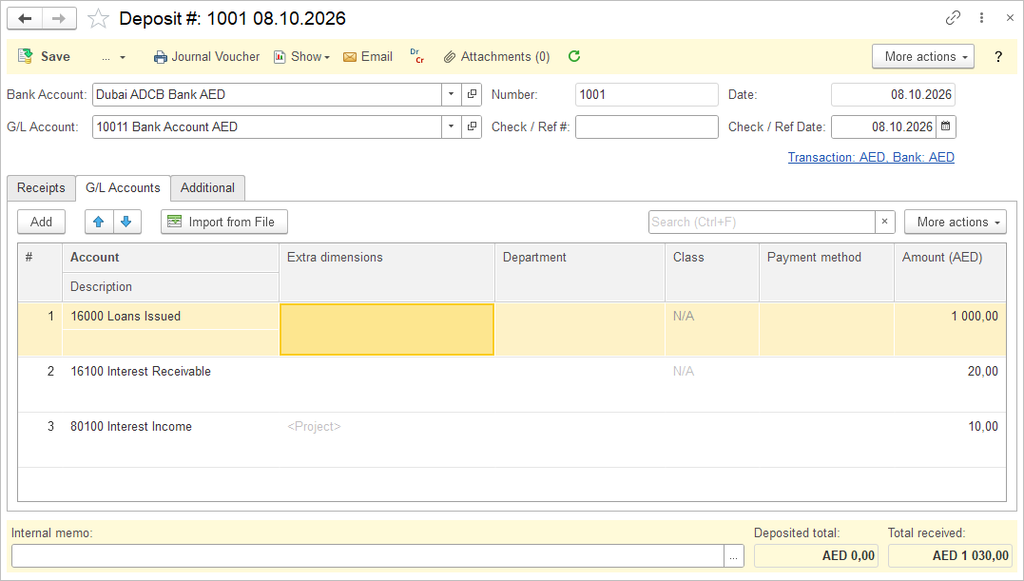
When the borrower pays back the loan, the payment usually consists of two parts: principal and interest. You must split the payment accordingly.
| Document | Debit | Credit |
|---|---|---|
| Deposit | 10000 Bank Accounts (or 10011 Bank Account Currency) | |
| 16000 Loans Issued (principal portion) | ||
| 16100 Interest Receivable or 80100 Interest Income (interest portion) |
If interest was already accrued in step 3, you credit 16100 Interest Receivable. If it was not accrued, you credit 80100 Interest Income directly.
5. Writing off an uncollectible loan (bad debt) #
If the borrower defaults and the loan is deemed uncollectible, the asset must be written off.
| Document | Debit | Credit |
|---|---|---|
| Journal Entry | 60800 Bad Debt | |
| 16000 Loans Issued | ||
| 16100 Interest Receivable |